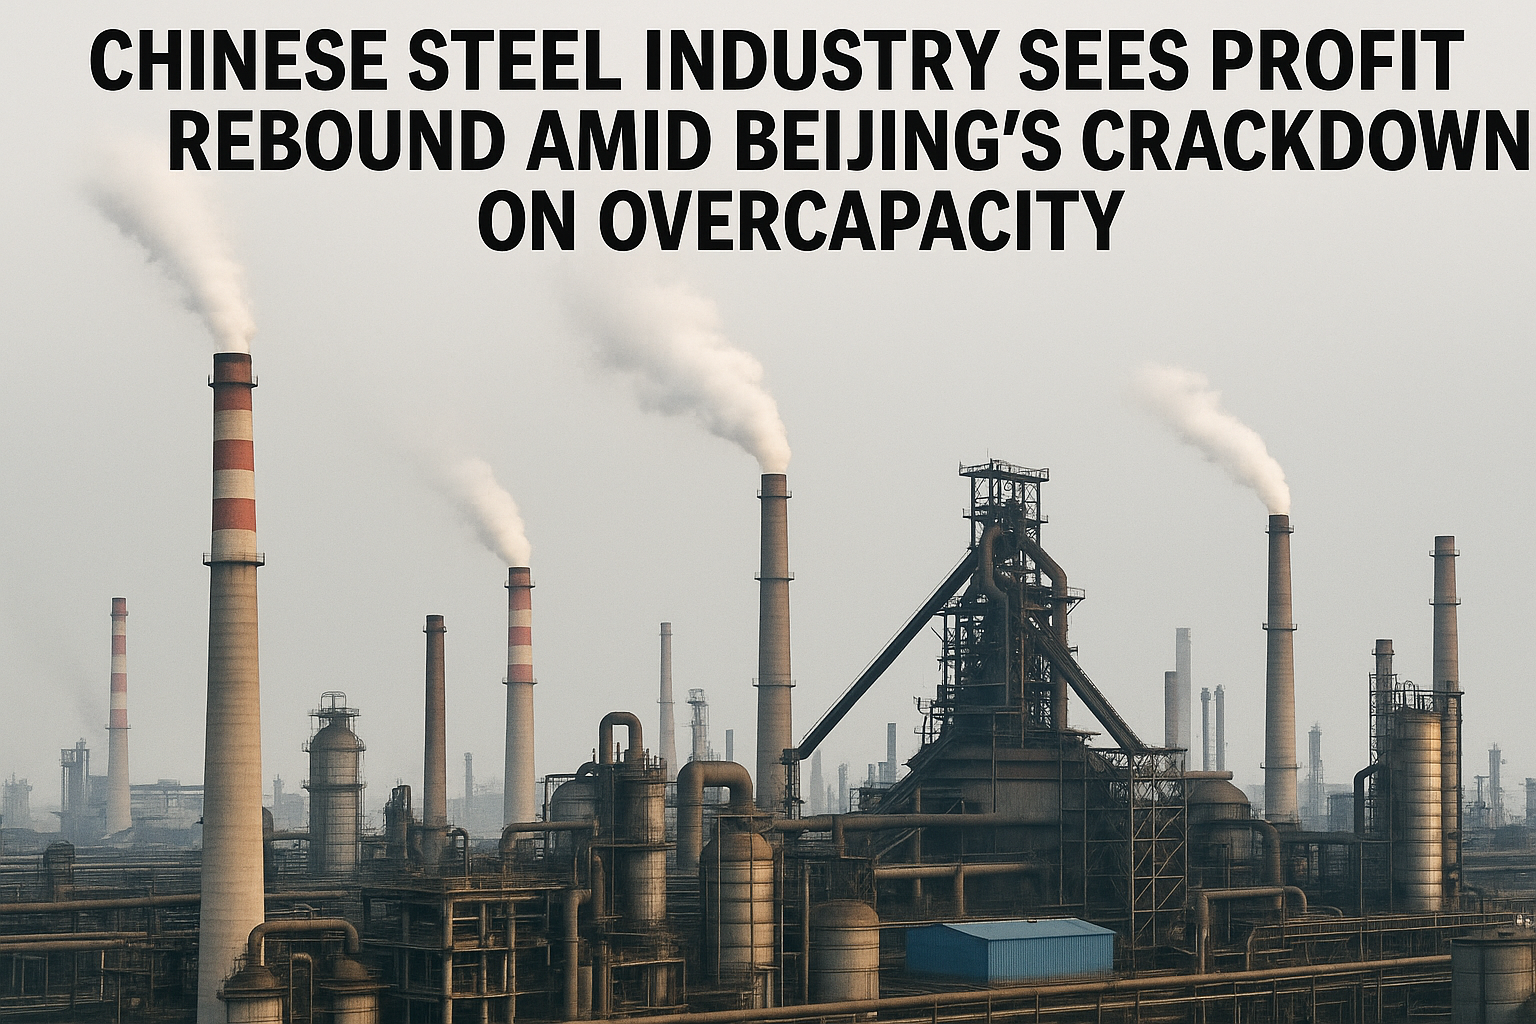
Chinese steel mills saw a rebound in profitability last month, with expectations that the recovery could gain momentum in the latter half of the year—provided the government follows through on its commitment to curb overcapacity.
As of mid-year, profits in the ferrous metal smelting sector had surged nearly 14 times compared to the same period last year, although from a relatively low base, according to data released by the statistics bureau on Sunday (July 27). Profit margins improved in June, aided by production cuts and weaker raw material prices relative to finished steel products.
The steel industry has faced significant challenges in recent years due to the collapse of China’s property sector, historically its main demand driver. This downturn has made the sector a key focus of Beijing’s campaign against excessive, inefficient competition—an effort that has intensified in recent weeks.
Although the industry has previously avoided strict capacity controls, there’s a renewed push from policymakers to address rampant competition across the broader economy.
While specific measures to address overcapacity are still under discussion, steelmakers appear to have taken preemptive action by significantly cutting production in June. This led to the lowest first-half output since 2020, raising uncertainty about whether the government will need to impose additional restrictions.
Meanwhile, demand is showing signs of recovery. Consumption rose 4.3% in the first half of the year, driven by increased activity in the automotive and machinery sectors, according to Bloomberg Intelligence (BI). Although construction remains a weak link, exports have remained strong despite global trade pressures, BI noted.
Looking ahead, prospects are improving—boosted by anticipated demand from projects like China’s massive dam construction in Tibet. According to UBS, over 60% of steelmakers are currently turning a profit, a sharp increase from just 30% in July 2024.
However, rising raw material costs, particularly the sharp increase in coking coal prices, may still pose a risk to sustained profitability.
